
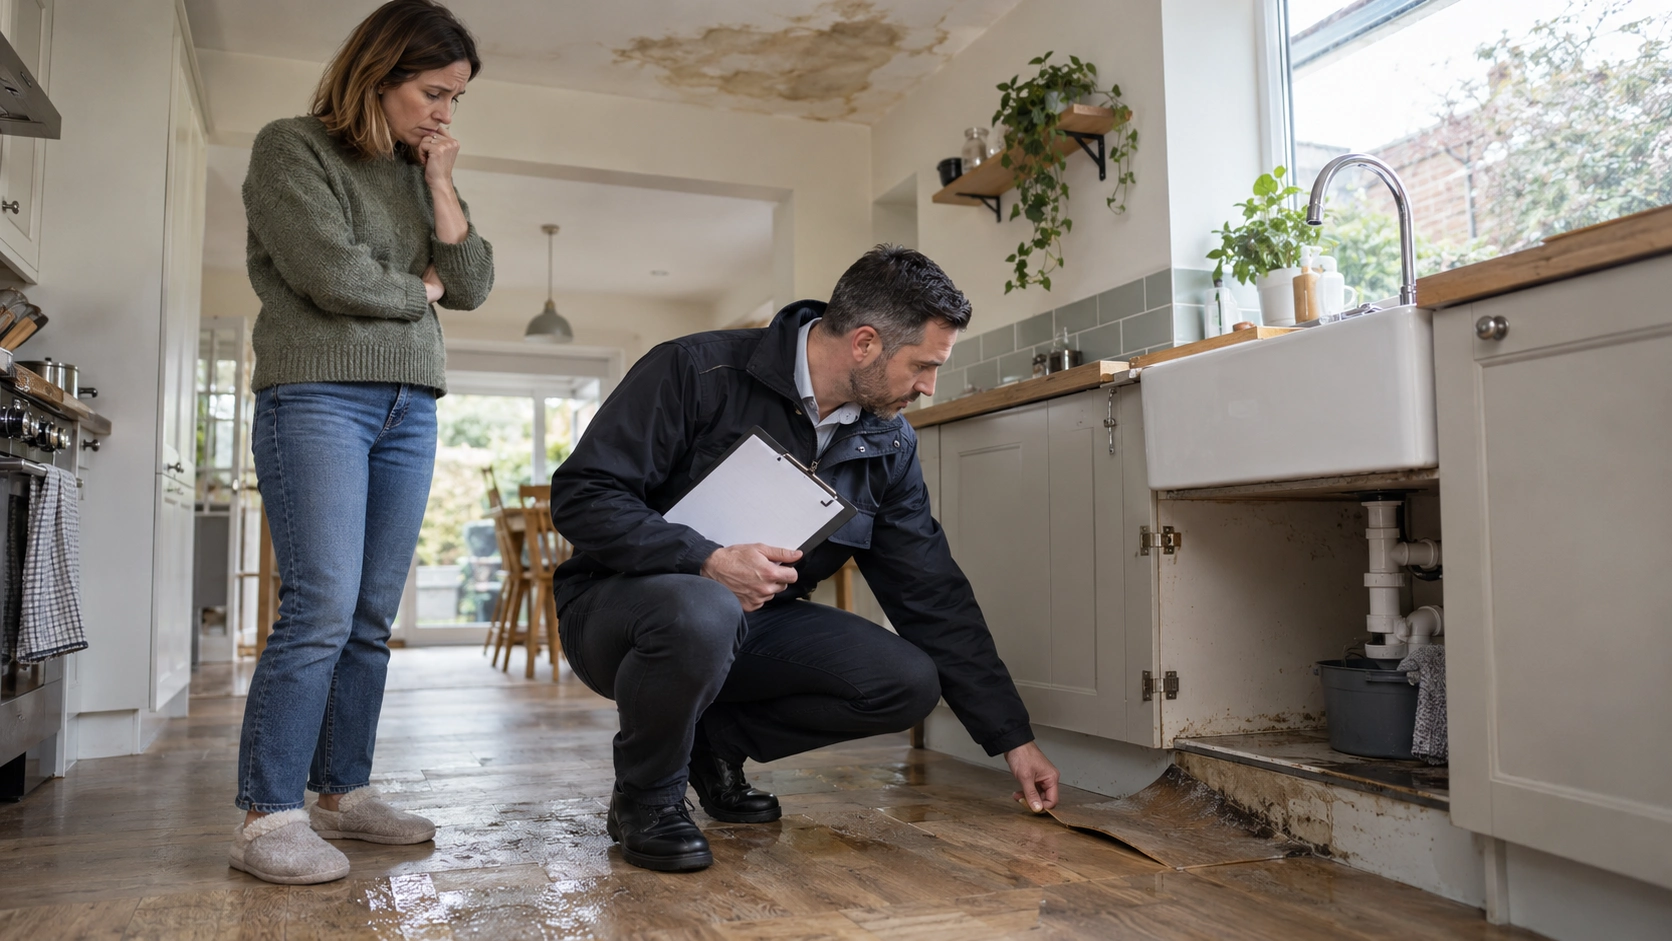
Discovering a burst pipe or a leaking appliance has flooded your kitchen or ceiling is stressful enough. Finding out afterwards that your insurer has rejected the claim outright, or offered a settlement that doesn’t come close to covering the repairs, can feel like a second blow entirely.
Unfortunately, this happens more often than most policyholders expect. The good news is that a rejected or underpaid claim isn’t necessarily the end of the road. There’s usually a reason behind the decision, and in many cases, that reason can be challenged.
What “escape of water” cover is actually meant to include
Most UK home and landlord insurance policies include escape of water as standard cover. In plain terms, it protects you when water escapes suddenly and accidentally from a fixed source, such as a burst pipe, a failed washing machine hose, an overflowing bath, or a leaking radiator.
The key word insurers focus on is “sudden.” Cover is generally designed for one-off, unexpected events rather than problems that have built up gradually over time. That distinction is where a lot of disputes begin.
Common reasons escape of water claims get rejected
The damage is classed as gradual, not sudden. If an insurer’s assessor decides a leak had been dripping slowly for weeks or months rather than happening suddenly, they may argue it falls under “wear and tear” or lack of maintenance, both of which are typically excluded.
Evidence of neglect or poor maintenance. If pipework, seals, or appliances were clearly old, corroded, or previously reported as faulty, insurers may argue the damage was foreseeable and could have been prevented.
The source of the leak is disputed. Escape of water claims often hinge on finding the exact point where water entered the property. If your insurer’s engineer and your own understanding of events don’t match, the claim can be downgraded or declined.
Underinsurance. If your buildings or contents sum insured doesn’t reflect the true rebuild or replacement cost, insurers can apply “average,” reducing your payout proportionally, even on a claim they’ve otherwise accepted.
Low-ball cash settlements. Some insurers offer a cash settlement instead of arranging repairs themselves. These figures are sometimes based on standardised repair costs that don’t reflect your property, your local contractor rates, or the full extent of the damage, including drying time, redecoration, and replacing damaged belongings.
What to do if you think the decision is wrong
- Ask for the decision in writing, with reasons. Insurers are required to explain why a claim has been declined or reduced. Don’t accept a verbal explanation over the phone; get it in an email or letter so you have something concrete to respond to.
- Gather your own evidence. Photos and videos from when you first discovered the damage, maintenance records, receipts for any relevant repairs, and correspondence with plumbers or contractors can all help build a clearer picture of what actually happened and when.
- Get an independent opinion on the cause and cost. Insurers’ loss adjusters work for the insurer, not for you. If their findings don’t match what you believe happened, or their repair estimate seems unrealistically low, an independent assessment can carry real weight in a dispute.
- Use the insurer’s formal complaints process. Every UK insurer has to have one. Put your case in writing, reference your policy wording directly, and be specific about what you’re disputing and why.
- Escalate to the Financial Ombudsman Service if needed. If your complaint isn’t resolved to your satisfaction, or you haven’t had a final response within eight weeks, you have the right to take the complaint to the Financial Ombudsman Service (FOS) free of charge. Insurers know this, and a well-evidenced case that’s heading toward FOS is often taken more seriously internally.
Why the insurer’s loss adjuster isn’t your advocate
It’s worth understanding this distinction clearly: a loss adjuster is appointed and paid by the insurer to assess your claim on their behalf. Their job is to protect the insurer’s position, not necessarily to secure the best outcome for you. That doesn’t mean every adjuster acts unfairly, but it does mean nobody in that process is working solely in your interest.
A loss assessor, by contrast, is appointed by you, the policyholder, to manage the claim on your behalf, negotiate directly with the insurer’s representatives, and make sure the settlement reflects the true cost of putting your property right. You can read more about how loss assessors work and why it matters.
If you’re still in the early stages of a claim, it’s also worth reviewing what to do immediately after property damage, since the evidence you gather in the first few days often ends up being what a dispute later hinges on.
Frequently Asked Questions
It’s much harder, but not always impossible, especially if you can show the insurer didn’t have the full picture when the settlement was agreed, or if further damage comes to light afterwards. It’s always better to query a decision before accepting it than to try to reopen the claim later.
This is one of the most common grounds for rejection, and one of the most contestable. A sudden pipe or appliance failure can still cause damage that looks like it built up gradually, particularly once water has spread through flooring or plaster. An independent assessment of the actual cause can challenge this classification where it isn’t clearly correct.
No. Insurers may offer a cash settlement as an option, but you’re not obliged to accept a figure that doesn’t reflect the real cost of repairs. If the offer seems low, you can ask for a breakdown of how it was calculated and challenge it with your own quotes or evidence.
There’s no single fixed deadline, but you shouldn’t leave it too long, both because evidence becomes harder to gather over time and because your policy may set its own time limits for reporting disputes. If your complaint to the insurer isn’t resolved, you generally have six months from their final response to refer it to the Financial Ombudsman Service.
Fees vary by provider and by the type of service, and it’s something you should always ask about upfront before agreeing to anything. Get in touch with UK Property Claims directly and we’ll talk you through exactly how it works for your claim before you commit to anything.
Not necessarily. A rejected claim can often still be challenged, particularly if the decision was based on an assessment you disagree with or evidence that wasn’t fully considered. The sooner you get independent advice after a rejection, the more options you typically have.
Getting help with a disputed claim
If your escape of water claim has been rejected, reduced, or is dragging on without a clear resolution, it’s worth getting independent advice before you accept a settlement or give up on the claim altogether. At UK Property Claims, we work exclusively for homeowners, landlords, and business owners, never for insurers, to make sure claims are assessed fairly and settlements reflect the real cost of repairs.
If you’re dealing with a disputed or underpaid escape of water claim, get in touch for a no-obligation conversation about your options.